How Long Does Term Life Approval Take? Timelines Explained
Get approved for term life in as little as 24 hours or up to 6 weeks. Call (833)-212-4240 to compare no-exam and traditional options fast.
By Nour Osman
You have finally decided to protect your family with term life insurance, but one question keeps nagging at you: how long does it take to get approved for term life? The answer can range from a few minutes to several weeks, and the difference often comes down to how the policy is underwritten. Understanding the timeline helps you plan ahead, avoid unnecessary delays, and choose a path that fits your urgency. Whether you are young and healthy or managing a chronic condition, knowing what to expect at each stage will make the process far less stressful.
Traditional Underwriting vs. Accelerated Underwriting
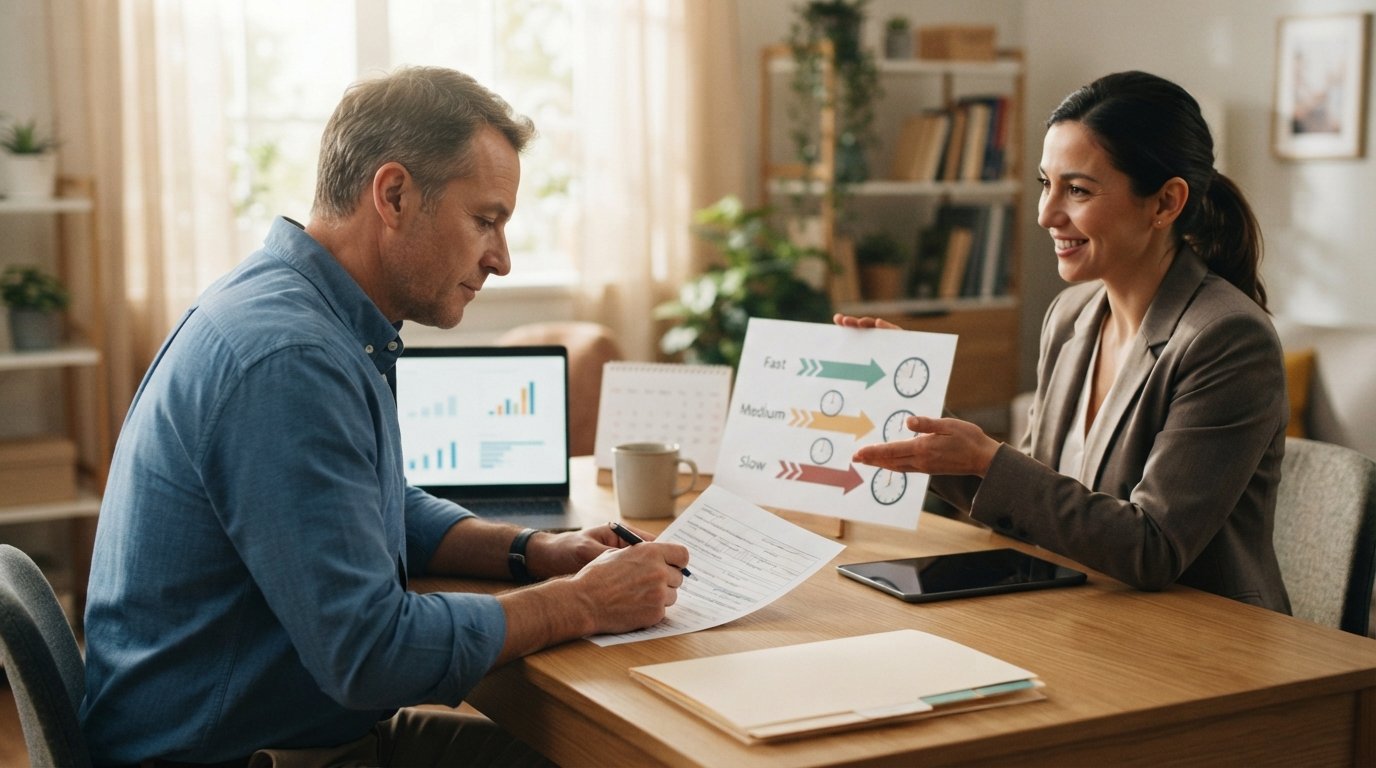
The traditional underwriting process is the most thorough route to approval, and it is also the slowest. After you submit an application, the insurer orders medical records, checks prescription databases, reviews your driving history, and may schedule a paramedical exam where a professional visits your home to collect blood and urine samples, measure height and weight, and record blood pressure. All of this information is compiled into a file that an underwriter reviews manually. The entire process typically takes three to six weeks, though it can stretch longer if records are slow to arrive or if the underwriter needs clarification on a health issue.
Accelerated underwriting, by contrast, uses data-driven algorithms to evaluate risk without the need for a medical exam in many cases. Insurers pull electronic health records, prescription histories, motor vehicle reports, and other databases to make a decision quickly. For applicants who meet certain criteria (typically younger ages, no significant health issues, and a clean background), approval can come in as little as 24 to 72 hours, and sometimes within the same day. This faster path is becoming increasingly common, especially for policies under $1 million and for applicants under age 60.
The key difference is not just speed but also the depth of review. Traditional underwriting leaves room for nuance: if you have a controlled condition like high blood pressure or a past surgery, a human underwriter can weigh the context and potentially offer a better rate. Accelerated underwriting relies on rules and data, so it may decline or table-rate applicants who fall outside the algorithm's comfort zone. Understanding these trade-offs helps you choose the right application path for your situation.
No-Medical-Exam Approval Speeds
No-medical-exam policies are designed for speed and convenience. These policies skip the paramedical exam and often rely on a simplified application with health questions and database checks. Approval timelines for no-exam term life insurance typically range from same-day decisions to about two weeks. Many carriers advertise "instant decision" or "fast approval" for qualified applicants, and some can issue a policy within minutes if your answers and data checks align with their criteria.
However, "no exam" does not always mean "no underwriting." Some no-exam policies still require a underwriter to review your application manually, which can add a few days. Others use a fully automated system that issues a decision immediately. The speed depends on the carrier, the coverage amount, and your health profile. For example, a 35-year-old non-smoker applying for $250,000 of coverage might get an instant approval, while a 55-year-old with a history of high cholesterol might need a few days for manual review.
It is also important to note that no-exam policies often have lower coverage limits. Many cap out at $500,000 or $1 million, and some final expense policies have limits as low as $25,000. If you need a larger death benefit, you may need to go through traditional underwriting, which takes longer. If speed is your top priority and your coverage needs are moderate, a no-exam policy can be an excellent choice.
Factors That Can Delay Approval
Even with the fastest underwriting path, certain factors can slow things down. Being aware of these potential roadblocks helps you set realistic expectations and take steps to mitigate them.
- Medical records requests: If the insurer needs records from your doctor's office, the response time can vary widely. Some offices respond within days, while others take weeks. You can help by providing accurate contact information for all your healthcare providers.
- Health history complexity: A history of cancer, heart disease, diabetes, or multiple chronic conditions often requires a more detailed review, which can add one to two weeks or more. The underwriter may need to request additional records or clarification from your physicians.
- Prescription history: The prescription database check may reveal medications that require explanation. If you have been prescribed a medication for a condition you did not disclose, the underwriter will need to follow up, causing delays.
- Motor vehicle records: DUIs, reckless driving, or multiple tickets can trigger a manual review and may require a longer lookback period.
- Foreign travel or residence: If you travel to certain countries or live abroad, the insurer may need to assess additional risk, which can extend the timeline.
- Incomplete application: Missing information, illegible handwriting, or unanswered questions can cause the application to be returned or put on hold.
In many cases, delays are simply a matter of paperwork and communication. Staying responsive to requests from the underwriter and providing complete information upfront can shave days or even weeks off the process.
How to Prepare for a Smooth Process
Preparation is your best tool for speeding up approval. Before you apply, gather the information you will need and consider how your health history will be evaluated. Here are steps you can take to streamline the process.
- Gather your personal and medical information: Have ready the names and contact details of all doctors you have seen in the past five to ten years, a list of medications you take (including dosages), and dates of any major surgeries or hospitalizations.
- Be honest and thorough on the application: Answer every question accurately. Omitting information can be considered misrepresentation and may lead to a denied claim later. If you are unsure about a detail, provide your best estimate and note that you are uncertain.
- Choose the right underwriting path: If you are healthy and need coverage quickly, ask about accelerated underwriting or no-exam options. If you have health issues, traditional underwriting may yield better rates, even if it takes longer.
- Schedule the paramedical exam promptly: If an exam is required, book it as soon as possible. Many services offer flexible scheduling, including evenings and weekends.
- Respond quickly to underwriter requests: Check your email and voicemail regularly. If the underwriter asks for additional information, provide it within a day or two.
Another smart move is to work with a service that connects you with licensed agents who can guide you through the process. For example, TermLifePlan makes it easy to request term life insurance quotes and explore coverage options. Licensed insurance agents walk you through term lengths and coverage amounts so you can choose a plan with confidence. Having an advocate who knows the underwriting quirks of different carriers can help you avoid common pitfalls and select a policy that suits your needs.
Typical Timelines at a Glance
To summarize, here is a realistic look at how long approval might take based on the underwriting method and your personal profile. Keep in mind that these are general estimates; individual experiences vary by carrier and circumstance.
- Accelerated underwriting (no exam): 1 to 3 business days, sometimes same-day.
- No-medical-exam with simplified issue: 1 to 2 weeks.
- Traditional underwriting with paramedical exam: 3 to 6 weeks on average.
- Traditional underwriting with complex health history: 6 to 8 weeks or more.
These timelines assume you submit a complete application and respond promptly to any requests. If you have a clean health profile and choose an accelerated path, you could have coverage in place by the end of the week. If you have multiple health concerns or need a large death benefit, plan for several weeks.
What Happens After Approval
Once the underwriter makes a decision, you will receive an offer. If you are approved at the rate you applied for, you simply pay the first premium and the policy goes into effect. If you are approved at a higher rate (a "rated" policy), you can choose to accept or decline. In some cases, the insurer may make a counteroffer with modified terms. After you accept, the policy is issued, and you will receive the documents. The time from approval to policy delivery is usually just a few days, but you can often request electronic delivery to speed things up.
It is also worth noting that some policies include a temporary insurance agreement (TIA) that provides coverage while the application is being underwritten, provided you pay the initial premium. This can bridge the gap if you need protection immediately. Ask your agent whether a TIA is available.
Common Questions About Approval Timelines
Can I speed up the process by paying more? Some carriers offer expedited underwriting for an extra fee, but this is not universal. The best way to speed things up is to choose the right underwriting path and be responsive.
Does my age affect the timeline? Older applicants often face more detailed review, which can add time. However, accelerated underwriting is increasingly available up to age 60 or even 65 with some carriers.
What if I need coverage urgently? If you need coverage within days, look for no-exam policies with instant decision capabilities. You may need to accept a lower coverage amount or a higher premium to get that speed.
How long does it take to get approved for term life if I have a pre-existing condition? It depends on the condition. Well-controlled conditions like hypertension or high cholesterol may still qualify for accelerated underwriting, while more serious conditions usually require traditional underwriting and may take four to eight weeks.
Understanding the timeline for term life approval empowers you to make informed decisions and avoid surprises. By choosing the right underwriting path, preparing your information, and working with knowledgeable professionals, you can secure the coverage your family needs without unnecessary delays. Whether you need a policy in place by next week or can wait a month, there is an option that fits your schedule and your budget.